- 01Court rulingon the emergency tariffs
- 02New duties appliedreplace the old ones
- 03Client book sortedrefund-exposed or not
- 04Entry papers pulledfor refund claims
The Supreme Court struck down IEEPA tariffs on February 20, 2026, ruling 6-3 in Learning Resources v. Trump that the statute does not authorize the President to impose tariffs. Replacement tariffs followed under other laws: a 10% Section 122 surcharge from February 24 to July 24, 2026, then Section 301 duties of 10% or 12.5% on goods from 60 economies. For a freight forwarder the fallout has 2 halves. The backward-looking half is refunds: U.S. Customs and Border Protection opened a refund tool, CAPE, on April 20, 2026, and says valid refunds generally issue within 60 to 90 days. The forward-looking half is rate confusion, because Section 232 tariffs and the suspension of the $800 duty-free exemption stayed in place while the IEEPA rates fell. The desk-level work is sorting which of your clients’ entries sit on which side of that line, and the clock on older entries is not generous.
Not legal advice. If your clients are pursuing duty refund claims or adjusting their filing posture based on the IEEPA ruling, direct them to licensed customs counsel. Facts in this post are from the Supreme Court opinion, the Federal Register and U.S. Customs and Border Protection pages, read on October 11, 2026.
Your inbox is getting hit from two directions right now. Importers are asking whether they can get money back. Shippers are asking what the current tariff rates actually are. Those are two different questions and they require two different answers.
What did the Supreme Court rule on IEEPA tariffs?
On February 20, 2026, the U.S. Supreme Court issued a 6-3 ruling in Learning Resources, Inc. v. Trump. Chief Justice Roberts, writing for the majority, held that the International Emergency Economic Powers Act does not authorize the President to impose tariffs. The taxing power belongs to Congress, and IEEPA’s language does not clearly delegate it.
The ruling covered every tariff the President had imposed under IEEPA, which Customs and Border Protection had collected since February 3, 2025. That includes the reciprocal tariffs and the IEEPA duties on products of China.
What did not change: Section 232 tariffs on steel, aluminum, heavy trucks, auto parts, and copper are still in effect. The suspension of duty-free treatment for shipments of $800 or less remains in place.
What tariffs replaced the IEEPA tariffs?
The White House moved the same day. Proclamation 11012 of February 20, 2026 invoked Section 122 of the Trade Act of 1974 and imposed a temporary import surcharge of 10% on most imports, effective February 24, 2026. The surcharge did not apply on top of Section 232 tariffs, and the proclamation listed other exceptions.
Section 122 caps a surcharge at 15% and limits it to 150 days unless Congress extends it. This one ran through July 24, 2026. On that same date, new Section 301 duties began: 10% or 12.5% on goods from 60 economies, including 12.5% on products of China, with exceptions listed in the tariff schedule.
For your clients and shippers, the pattern matters more than any one rate. The legal basis for these duties changed twice in 2026, and each change moved the number on the quote.
Can importers get refunds on IEEPA tariffs they paid?
The Court did not order automatic refunds. Justice Kavanaugh, in dissent, warned that the refund process is likely to be a “mess.” CBP’s answer came 2 months later.
On April 20, 2026, CBP launched the Consolidated Administration and Processing of Entries tool, CAPE, inside its ACE system. The importer of record, or the customs broker that filed the entries, uploads a list of entries on which IEEPA duties were paid. One declaration holds up to 9,999 entries. CBP removes the IEEPA line, liquidates or reliquidates the entry, and pays the refund with interest. CBP says valid refunds generally issue within 60 to 90 days of acceptance, and it charges no fee.
CBP is opening CAPE in phases. Phase 1 covers unliquidated entries and entries liquidated within the preceding 80 days. For those entries, CBP says an importer does not need a case at the U.S. Court of International Trade to receive a refund. For older liquidated entries CBP gives no legal guidance.
The protest window under standard CBP procedures is 180 days from liquidation. For entries liquidated long ago, that window may have closed. Your clients’ customs attorneys need to review those entries against the liquidation dates before drawing any conclusions about what is recoverable.
How do you sort a client book into refund-exposed and unaffected?
The sorting logic is mechanical once it is stated plainly, which is exactly what makes it work as a desk checklist rather than a legal research project. An entry is potentially refund-exposed when all 3 conditions hold: it was filed while the IEEPA rates were in force, it paid duties under an IEEPA heading in Chapter 99 of the tariff schedule, and its liquidation status still allows an administrative path. An entry is unaffected when its duties came from authorities the ruling left standing, Section 232 on steel, aluminum, and the extended product list, Section 301 where applicable, or ordinary MFN rates.
The practical difficulty is that a forwarder’s records rarely tag entries by statutory authority; they tag them by client, lane, and date. So the first pass runs on dates and commodities: pull entries filed during the IEEPA window, then split by whether the commodity’s duty burden actually came from the struck programs. For a client importing steel fixtures, most of the burden may sit under Section 232 and survive; for a client importing toys from China, the struck reciprocal rate was likely the whole story. That split is exactly the kind of document-and-date work that consumes an afternoon per client when the entry files live in email threads, and minutes when they are already bound to jobs. A book of 25 active importers is 25 of those sorting passes, which is the difference between answering every refund inquiry this week and triaging them into next month while the refund clock runs.
Two cautions for the client conversations, both cheap to observe now and expensive to walk back later. Do not promise refunds; eligibility runs through CBP’s refund process and its deadlines, and it belongs with the customs broker or counsel. And do not let the refund conversation obscure the forward-looking one: the client’s landed cost model needs updating for the replacement tariffs either way, and the client who hears only “you might get money back” will budget next quarter on the wrong rates, and remember who let them.
What should a freight forwarder do about the IEEPA ruling?
Your clients do not necessarily know the difference between IEEPA tariffs, Section 232 tariffs, Section 122 surcharges, and liquidation deadlines. They know they paid a lot in duties over the past year and a half and they saw a news headline about a court ruling.
A few things to do now:
Know what your clients imported and when. Before you can tell any importer whether they have a refund opportunity, you need entry dates, HTS codes, and an understanding of which tariff lines those entries were classified under. Your TMS has this. If it does not, the ACE portal does.
Do not give legal opinions. What you can say: “We are reviewing which entries were classified under IEEPA-affected codes and can flag the relevant ones for your customs attorney.” What you cannot say: “You probably have a claim.”
Communicate clearly about current rates. The Section 122 surcharge ended on July 24, 2026. Section 301 duties of 10% or 12.5% on goods from 60 economies began that day, and Section 232 tariffs continue. Check the rate for each product and origin before you quote.
Expect the next change. The legal basis for these duties changed twice in 2026. Clients with long lead times on import orders need a rate check before each booking.
Point refund-eligible clients to their broker now. The importer of record or its broker files the CAPE declaration. For entries already liquidated, the 80-day and 180-day limits are short, and those cases need trade counsel.
How do forwarders pull entry documents for refund claims fast?
A CAPE declaration needs the list of entries on which IEEPA duties were paid. A protest on an older entry also needs the original entry summaries, commercial invoices, packing lists, and HTS classification evidence. For shipments from 2025, that documentation exists somewhere. Finding it under inbox pressure is where things break down.
The forwarders who handle this cleanly will be the ones whose job records are tied to their email history well enough that pulling documents for a specific entry takes minutes. If your current workflow has that material spread across email threads, network drives, and TMS notes with no reliable link between them, this is the moment that surfaces the gap.
Managing the inquiry volume that comes with events like this is exactly the kind of problem TIO was built for: answering your staff’s questions about a load from your records, and surfacing the relevant document history. Inbox triage, which sorts a shared mailbox, is in pilot and sends nothing. If you want to see how that works with your TMS setup, book a demo.
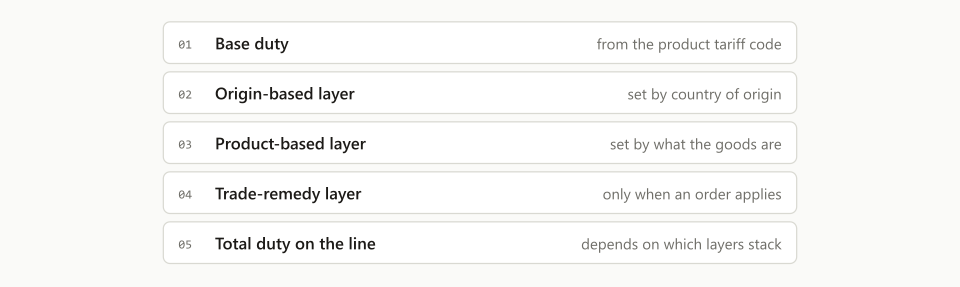
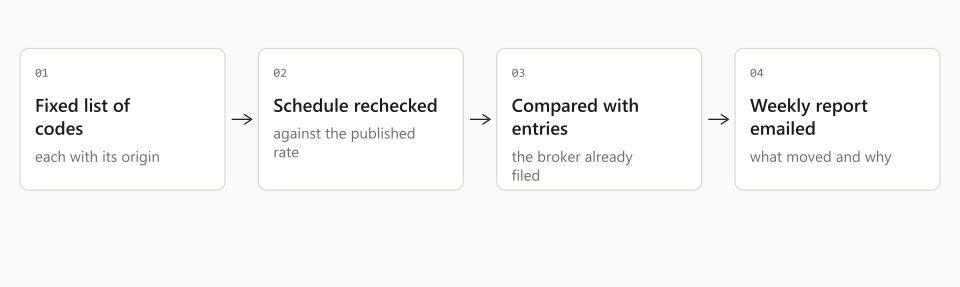
For the weekly check that catches a rate change before the next quote, see the weekly HTS code and duty rate audit. For how the duty layers that remain combine on one line, see what tariff stacking is.
TIO is an AI agent workforce for freight forwarders and 3PLs: named agents that quote freight, create lots and delivery orders, and reconcile charges from the inbox your team already uses. Meet the agents.
Frequently asked questions
What is the IEEPA tariff ruling and what changed for freight forwarders?
The Supreme Court struck down tariffs imposed under the International Emergency Economic Powers Act on February 20, 2026. New tariffs replaced them the same day under separate statutory authority. For freight forwarders, the ruling created a window for duty refund claims on affected entries and triggered a surge of client inquiries about classification, routing alternatives, and landed cost changes.
Can importers claim refunds on tariffs paid under the IEEPA structure?
Yes, through U.S. Customs and Border Protection. CBP launched a refund tool called CAPE on April 20, 2026. The importer of record or its customs broker uploads a list of entries, up to 9,999 per declaration, and CBP says valid refunds generally issue within 60 to 90 days of acceptance. Phase 1 covers unliquidated entries and entries liquidated within the preceding 80 days. Older entries may need a protest, which is due 180 days from liquidation, and belong with customs counsel. The forwarder's role is locating the entries, not filing the claim.
What happened to the Section 122 surcharge on July 24, 2026?
Section 122 of the Trade Act of 1974 allows a temporary import surcharge of up to 15% for up to 150 days. The 10% surcharge began February 24, 2026 and ran through July 24, 2026. On that date new Section 301 duties of 10% or 12.5% began on goods from 60 economies, with listed exceptions. Each date set off a round of shipper inquiries and requotes for freight forwarders.
How should freight forwarders prepare their back office for tariff-driven RFQ surges?
The preparation that matters most is compressing response time on individual RFQs. When 20 quote requests arrive the same day, the forwarders who respond within two hours take the bookings. That requires reducing the inbox-coordination time per RFQ, not just having access to rates, since reading the email and extracting the lane details is where time actually goes.